The seller has accepted your offer, but the home is not yours just yet. Understanding what happens after offer acceptance can replace a lot of nervous waiting with clear next steps. In the Oklahoma

Dated: September 20 2026
Views: 4
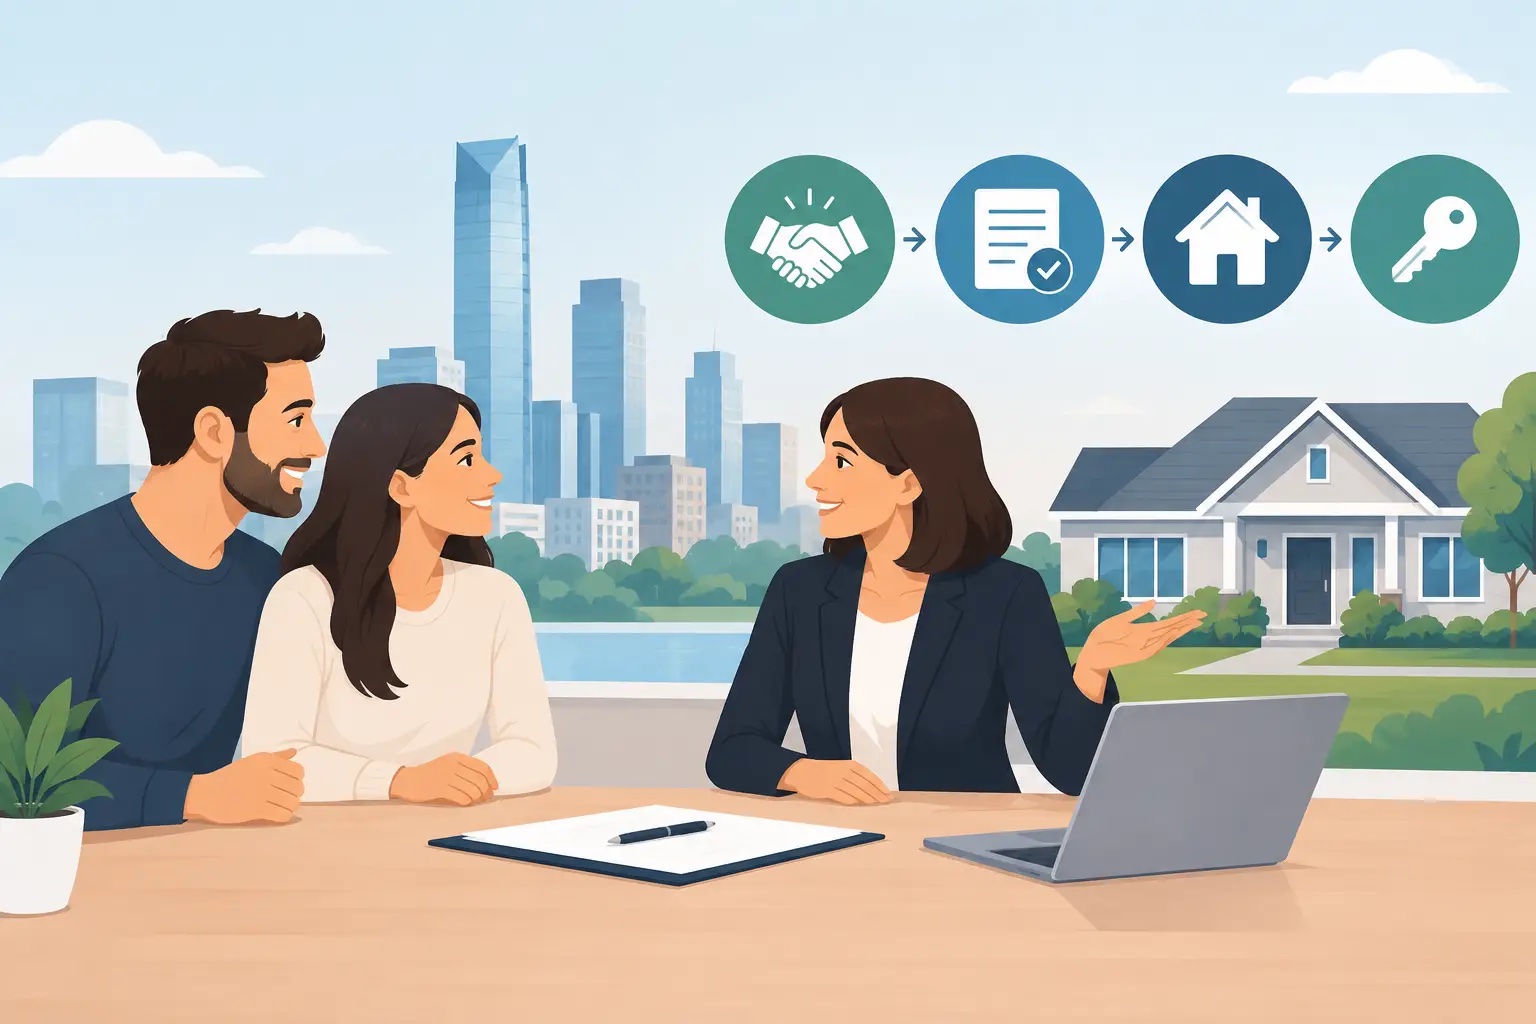
The seller has accepted your offer, but the home is not yours just yet. Understanding what happens after offer acceptance can replace a lot of nervous waiting with clear next steps. In the Oklahoma City metro, the period between acceptance and closing is when your agent, lender, title company, inspector, and appraiser work through the details that make a sale ready to close.
For buyers, this is the due-diligence and financing phase. For sellers, it is the period when the contract moves from an agreed price to a completed transaction. Deadlines matter, and prompt communication can make a meaningful difference when questions or issues come up.
Once all parties have signed the purchase contract, your REALTOR® distributes the executed contract to the people who need it, typically including the lender and title company. The contract establishes the purchase price, financing terms, earnest money, inspection rights, requested closing date, and any special provisions negotiated with the seller.
The first practical task is usually earnest money. Your contract will specify the amount and where it must be delivered. In many Oklahoma transactions, the earnest money is held by the title company. It is not an extra fee added to your purchase price. If the sale closes, it is generally credited toward your funds due at closing. What happens if a contract ends before closing depends on the contract terms, deadlines, and reason for termination, so do not make assumptions before speaking with your agent.
Your agent will also keep a close eye on the calendar. Inspection periods, financing contingencies, appraisal-related deadlines, and title objections all have time limits. A home purchase has several moving parts, but good transaction management keeps each one visible before it becomes urgent.
Most buyers schedule a general home inspection shortly after the offer is accepted. In a competitive market, some buyers may limit or waive certain inspection rights, but that is a decision with real risk and should be made with a clear understanding of the property and the contract.
A general inspector evaluates accessible components such as the roof, HVAC system, electrical panel, plumbing, foundation conditions, appliances, attic, and visible signs of moisture or damage. The inspection is not a guarantee that every issue will be found, nor is it a pass-or-fail test. Its purpose is to help you understand the home's condition and make informed decisions.
Depending on the property, you may also want specialized inspections or estimates. Older Oklahoma City homes, acreage properties, homes with wells or septic systems, and properties with visible drainage concerns can require a closer look. A sewer scope, pest inspection, structural evaluation, roof assessment, or HVAC opinion may be appropriate based on the initial findings.
If the inspection reveals concerns, you and your agent can discuss the available paths. You might proceed as written, ask the seller to make certain repairs, request a credit when allowed and appropriate, renegotiate, or terminate within the rights and timeline provided by the contract. Sellers do not have to agree to every request, and buyers should focus on material concerns rather than treating an inspection report as a maintenance wish list. Nearly every home has items worth monitoring.
Preapproval helped you write a competitive offer. After acceptance, your lender begins the formal underwriting process. Expect requests for updated pay stubs, bank statements, tax documents, identification, and explanations for deposits or changes in employment. Responding quickly matters because underwriting cannot move forward without complete documentation.
One of the simplest ways to protect your loan approval is to keep your financial picture stable. Avoid opening new credit accounts, financing furniture or a vehicle, moving large sums of money without a paper trail, or changing jobs unless you have discussed it with your lender first. Even a well-intended purchase can affect debt-to-income ratios or create documentation questions.
The lender will also order an appraisal. The appraiser provides an independent opinion of the property's value for the lender. This is different from an inspection: an inspection looks at condition and possible defects, while an appraisal considers value based on the home, its features, and comparable recent sales.
If the appraisal meets or exceeds the contract price, the loan process usually continues as planned. If it comes in low, the buyer and seller may renegotiate the price, the buyer may bring additional funds if qualified and willing, the parties may challenge the appraisal with relevant information, or the transaction may end if contract protections apply. The right response depends on the appraisal gap, financing terms, and how much each party wants the home to close.
While the lender handles financing, the title company researches the property's ownership history. It looks for matters that could affect your right to own the home, such as unpaid liens, judgments, probate issues, or recording errors. The title company also prepares the closing documents and coordinates the transfer of funds.
You will receive a title commitment before closing. This document identifies the current owner, legal description, exceptions, and requirements that must be satisfied for title insurance. Read it carefully and ask questions about anything you do not understand, especially easements, restrictions, or survey-related items. An easement may be routine, such as utility access, but it can still affect how you use part of the property.
If you are buying in a neighborhood with a homeowners association, review the association documents, rules, fees, and any transfer requirements. Verify details that matter to your plans, including parking, rental restrictions, exterior changes, pet rules, and amenity access. A home can be a great fit physically while the association rules are not a fit for your lifestyle.
As closing approaches, your lender issues a Closing Disclosure for review. This document outlines your final loan terms, projected monthly payment, cash needed to close, and closing costs. Compare it with your Loan Estimate and ask about changes. Some numbers can shift as final figures are confirmed, but you should understand where your money is going before signing day.
You will also arrange homeowners insurance and provide proof to your lender. Utility transfers should be scheduled so service begins in your name on the appropriate date. If the home is vacant or you are relocating, confirm how keys, garage remotes, gate codes, and any access devices will be delivered.
A final walkthrough usually occurs shortly before closing. This is not another inspection. It is your chance to verify that the home is in substantially the expected condition, agreed repairs have been completed, and the seller has moved out unless the contract says otherwise. Bring the repair agreement and receipts or invoices if repairs were negotiated. If something is not right, raise it immediately so your agent can address it before documents are signed.
For sellers, accepting an offer begins a different kind of preparation. The home needs to remain in the condition required by the contract, agreed repairs need to be completed on time, and access must be provided for inspections, appraisal, and final walkthroughs. Keep repair receipts and avoid removing fixtures, appliances, or items that were included in the sale.
Sellers should also watch for title-company requests, payoff information for mortgages or liens, and questions about property disclosures. Moving plans deserve attention early. Last-minute packing, utility shutoffs, or missed repair appointments can put unnecessary pressure on an otherwise solid transaction.
Not every accepted offer reaches closing without a conversation. Inspection findings, appraisal gaps, underwriting questions, title issues, repair delays, and survey concerns are all possible. Most are manageable when the parties receive clear information and have time to consider practical options.
The key is not to let uncertainty sit. Tell your agent when a lender requests something unusual, when a repair is incomplete, or when you are concerned about a document. A responsive local REALTOR® can help you understand what is normal, what deserves follow-up, and what choices the contract gives you. Cameron John helps buyers and sellers across the Oklahoma City metro stay informed through these moments rather than guessing their way through them.
At closing, you will sign the deed-related, loan, title, and settlement documents required for the transaction. Bring the identification requested by the title company and confirm in advance how closing funds must be delivered. Wire fraud is a serious concern, so always verify payment instructions directly with the title company using a trusted phone number before sending money.
After documents are signed and funds are received, the title company completes funding and recording steps. The exact timing for keys depends on the contract and closing arrangements. In many cases, possession is delivered at closing or after funding, but it can differ if the parties have negotiated a post-closing possession agreement.
The best next step after acceptance is simple: stay reachable, meet each deadline, and ask questions before a small concern becomes a closing-day surprise. A well-managed transaction gives you room to focus on the part that matters most - settling into a home you feel good about.
Why choose Cameron John as your REALTOR®? Cameron John is a dedicated RE/MAX Preferred REALTOR® who combines experience, energy, and a deep commitment to helping home buyers find the perfect place ....
The seller has accepted your offer, but the home is not yours just yet. Understanding what happens after offer acceptance can replace a lot of nervous waiting with clear next steps. In the Oklahoma
EDGEMERE PARK · OKLAHOMA CITYA 1931 Bungalowwith Enduring Character114 NW 31st Street · Oklahoma City, Oklahoma2 BEDROOMS | 1 BATHROOM |
A home in Edmond can look great online, receive a few saves, and still sit without a showing. A well-kept Yukon home may have steady traffic but no offers. That is when sellers start asking, when
Mustang real estate appeals to people who want more room, a connected community, and convenient access to Oklahoma City without living in the middle of the metro. For buyers, the challenge is often
 Copyright© 2026 MLSOK, Inc. listing content is believed to be accurate but is not guaranteed. Subject to verification by all parties. The listing information being provided is for consumers personal, non?commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. This listing data is copyrighted and may not be transmitted, retransmitted, copied, framed, repurposed, or altered in any way for any other site, individual
and/or purpose without the express written permission of MLSOK, Inc. Information last updated on September 20, 2026 6:12 PM UTC
© 2026 OKC Metropolitan Association of REALTORS® (OKMAR). All rights reserved.
Disclaimer: All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) nor September 20, 2026 6:12 PM UTC shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless.
Data last updated on September 20, 2026 6:12 PM UTC
Show More...
